
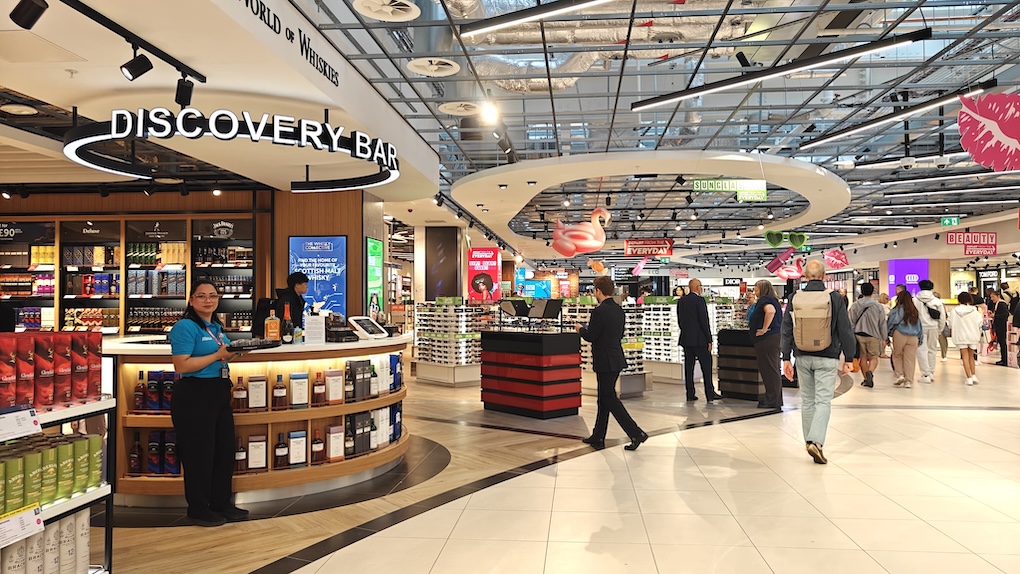
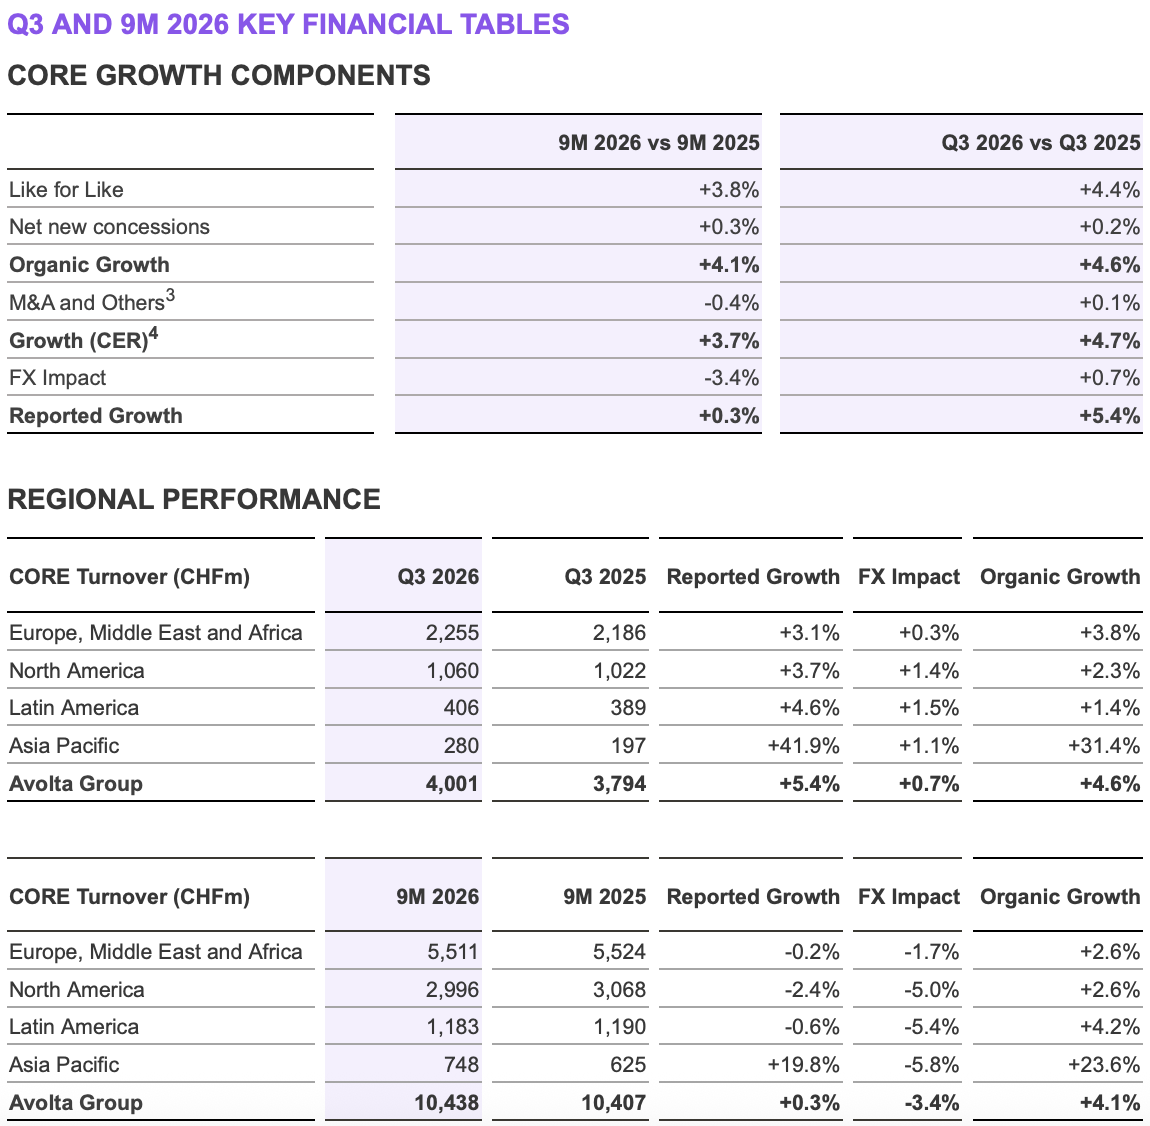
INTERNATIONAL. Leading travel retail and dining player Avolta today (29 October) announced a nine-month trading update to 30 September, with core turnover climbing +3.7% year-on-year at constant exchange rates and +4.1% on an organic basis to CHF10,438 million (US$12,602 million).
Excluding the impact of the Middle East war, nine-month organic growth would have been +5.2%.
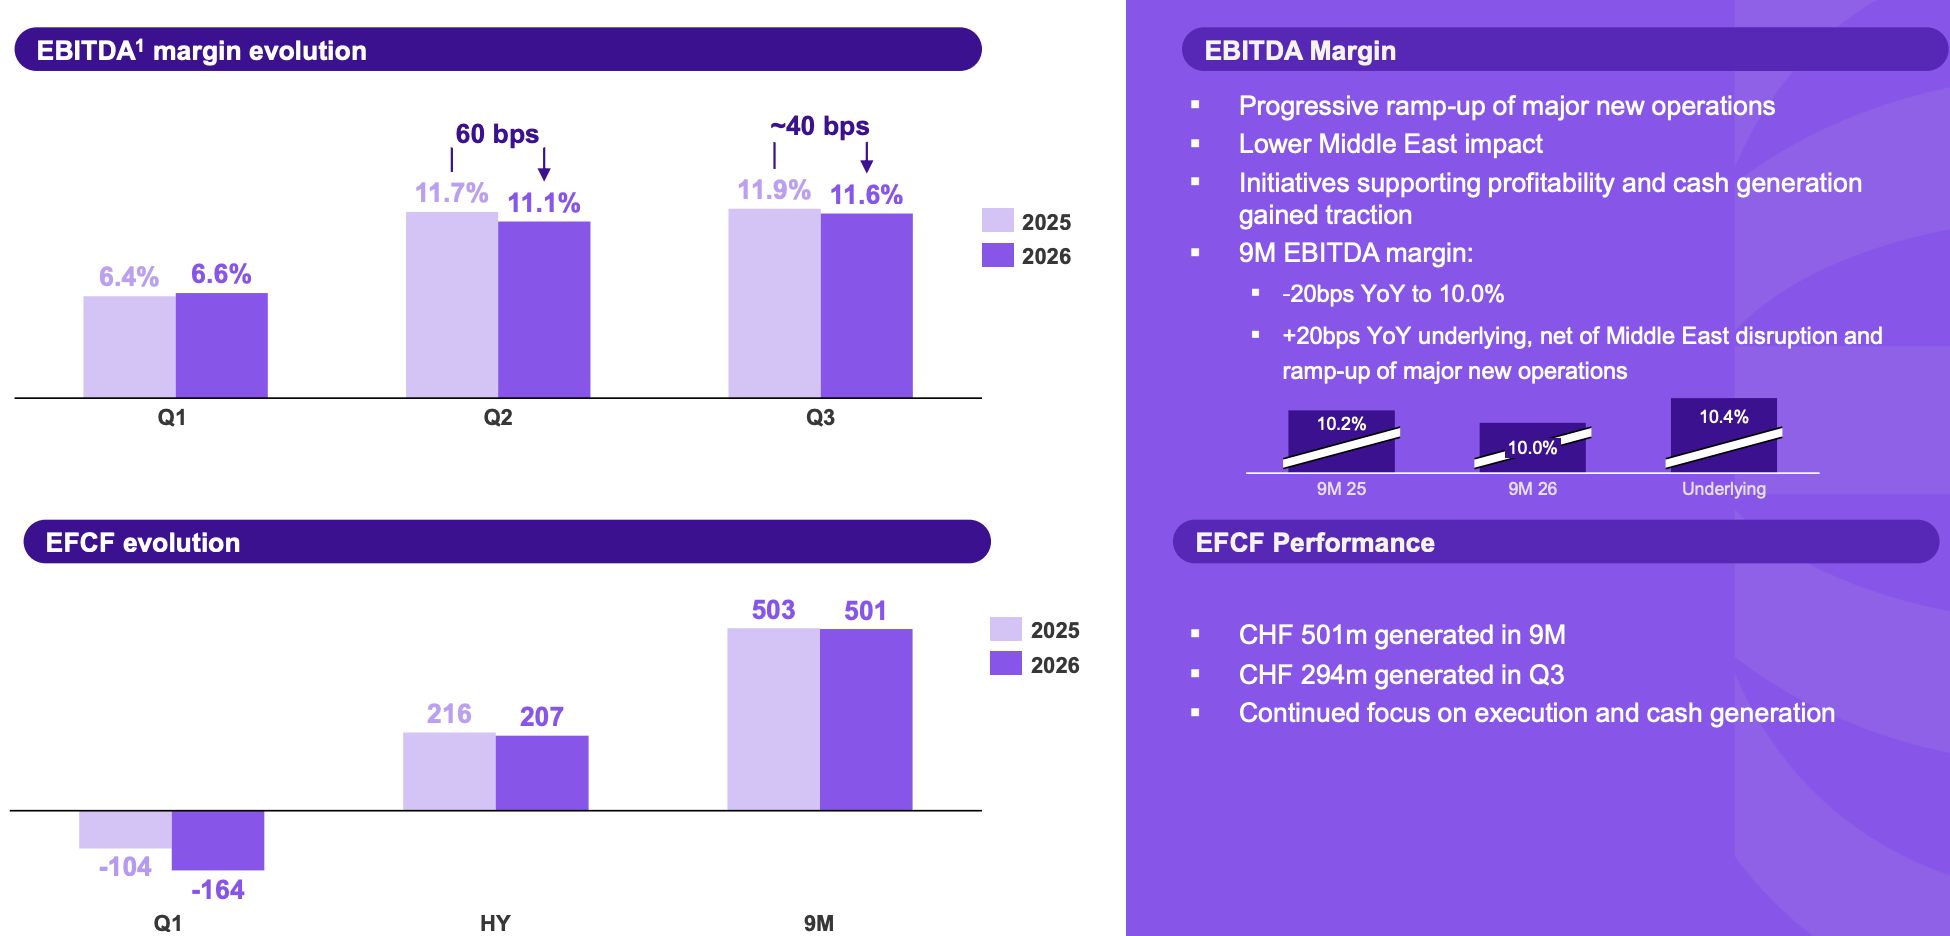
Revenue performance accelerated in Q3 with organic growth hitting +4.6% year-on-year compared with +2.9% in Q2. This was led by a +31.4% leap in organic growth in Asia Pacific, with Europe, Middle East and Africa at +3.8%, North America at +2.3% and Latin America at +1.4%.
Reported growth climbed +5.4% year-on-year in Q3.
Of the third-quarter revenue performance, the company stated: “M&A and Others turned positive as strategic investments began to contribute.”
Avolta noted that preliminary October figures show organic growth around +4%, with all regions contributing.
Nine-month core EBITDA reached CHF1,044 million (US$1,260 million) at a 10% margin, down by 20 basis points year-on-year, but with improvement in Q3.
The company noted: “Profitability remained affected by the Middle East disruption and the ramp-up of major new operations. These impacts moderated during Q3 as the new operations continued to ramp up and initiatives to support profitability and cash generation gained traction. Excluding these headwinds, the nine-month EBITDA margin would have increased by +20bps year-on-year to 10.4%.”
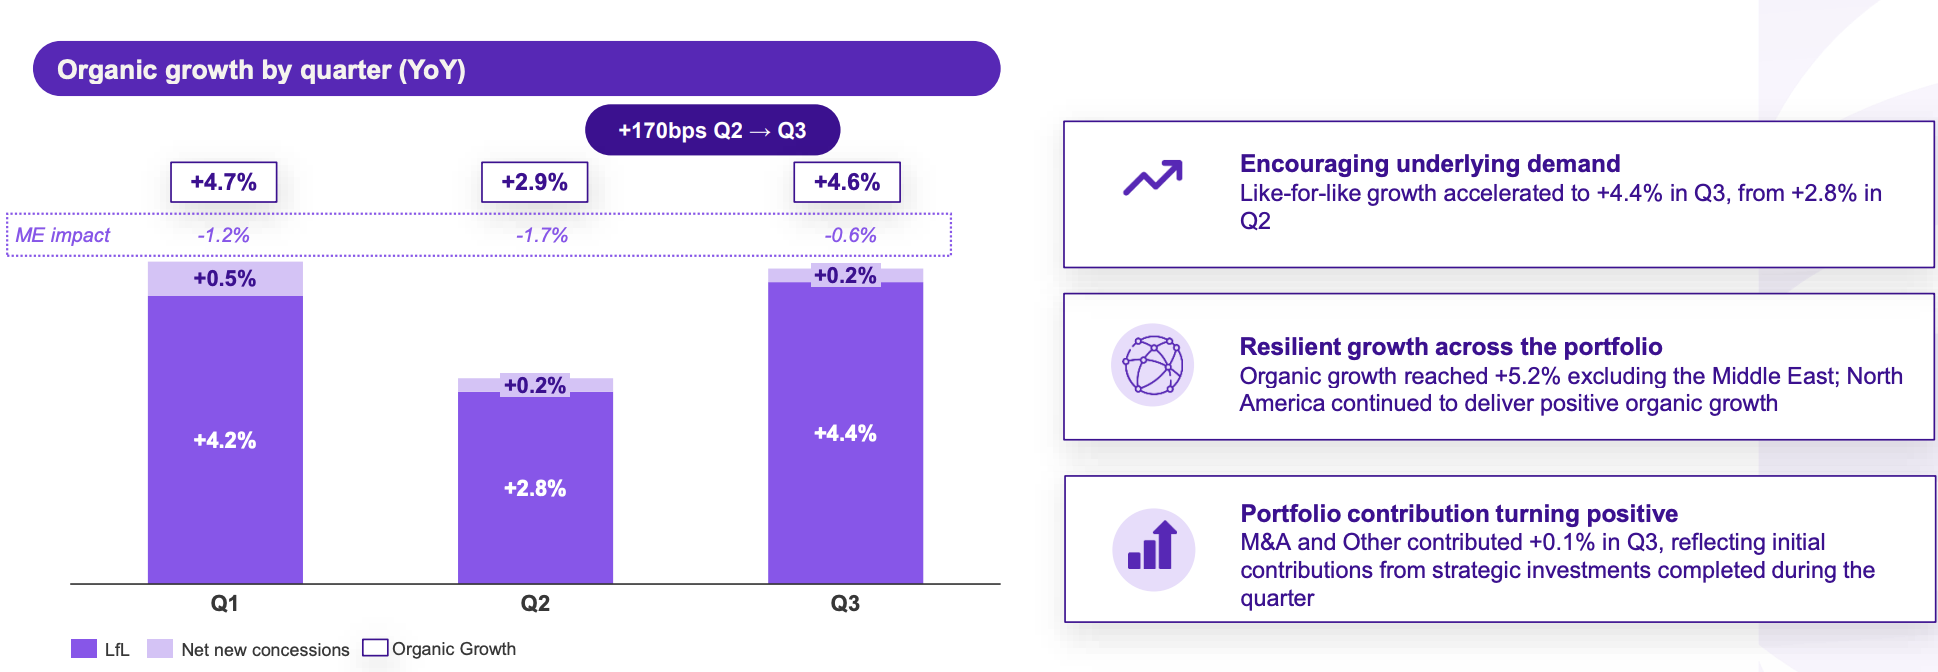
Equity Free Cash Flow (EFCF) amounted to CHF501 million (US$605 million), flat year-on-year, with Q3 at CHF294 million (US$355 million), +2.4% year-on-year, “continuing the progressive recovery quarter on quarter”, said the company.
Group financial net debt was CHF2,728 million (US$3,294 million) at the end of September 2026 and implies a leverage ratio (net debt/CORE EBITDA) of 2.0x. This reflects the acquisitions of both DFS Okinawa and Penha Duty Free (each completed in the last quarter) plus the purchase of shares totalling CHF191 million (US$231 million) under Avolta’s 2026 share buyback programme.
Avolta CEO Xavier Rossinyol said: “Our third-quarter performance was encouragingly resilient and demonstrated an improving momentum of the business. Organic growth accelerated in Q3 and remained strong into October.
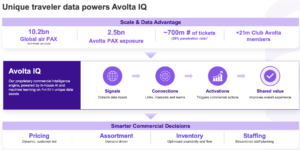
“At the same time, the profitability gap versus last year narrowed as new operations ramped up and our initiatives to support profitability and cash generation gained traction, alongside our continued focus on technology, digital and data transformation to further improve the business.
“On our resilient foundations, we remain focused on converting this progress into profitable growth and strong cash generation. We continue to invest selectively in attractive growth opportunities while returning capital to shareholders. This performance reinforces our confidence in Avolta’s medium-term targets.”
Avolta confirmed its medium-term targets of +5% to +7% organic growth per year, +20-40 basis points (bps) of annual Core EBITDA margin improvement and +100-150 bps of annual EFCF conversion improvement. Based on current exchange rates, currency translation is expected to have -2% negative impact on reported 2026 turnover versus 2025. ✈