
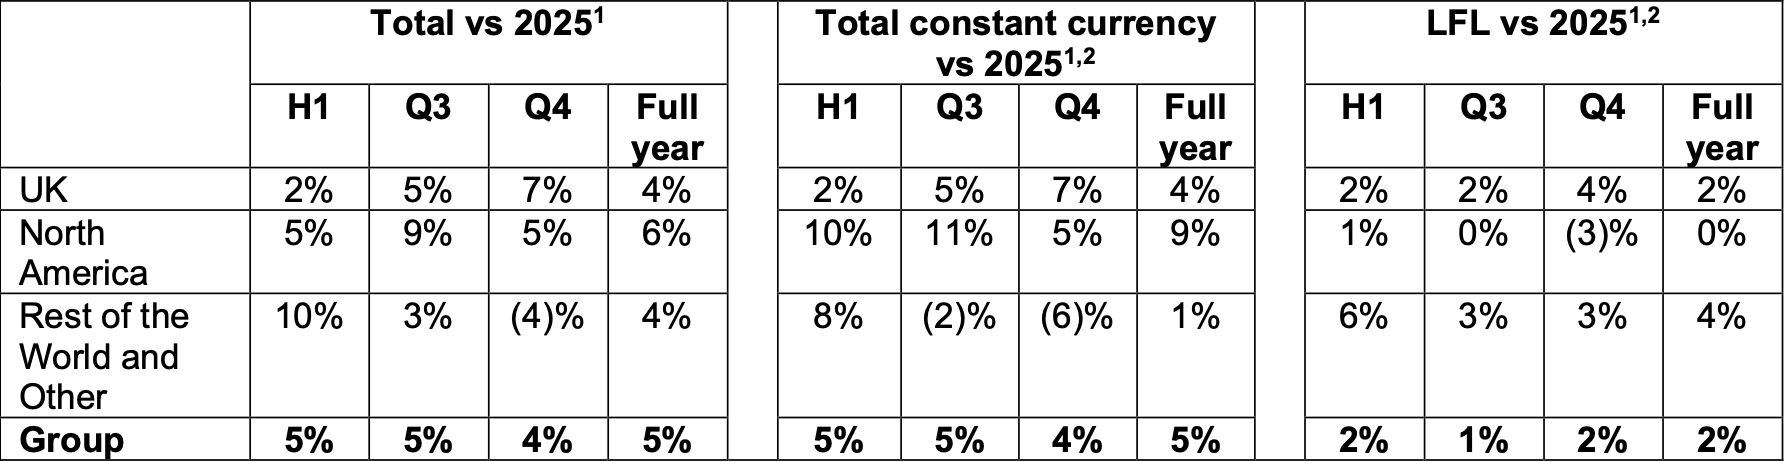
UK. Leading travel retailer WHSmith has issued a trading update for the year ended 31 August, with group revenue climbing by +5% year-on-year (unaudited) and like-for-like (LFL) revenue up +2% at constant currency rates. WHSmith reports preliminary results in November.
Amid continuing uncertainty from the Middle East conflict and a difficult year in North America, the company said it expects to deliver headline group profit before tax and non-underlying items of £75 million (US$100 million) for the year. This compared to £110 million (US$147 million) in the last financial year.
A statement said, “This reflects lower trading profit margins driven by increased promotional activity, a reduction in brand marketing and inflation headwinds, offset by central cost reductions and lower interest costs.”
In the UK division, revenue in Q4 increased by +7% with LFL revenue up +4%. By channel, Air saw revenue increasing by +7% and LFL revenue up +2%, supported by passenger growth and higher spend per passenger.
The Hospital channel delivered revenue growth of +9% in the fourth quarter and a LFL revenue uplift of +8%. Rail posted a revenue rise of +5% and LFL revenue up +4%.
Six one-stop-shops were opened in the financial year ahead of the peak trading season, including refurbished stores at Heathrow, Liverpool, Belfast International and East Midlands airports.
Q4 revenue in North America increased by +5%, up +5% on a constant currency basis, with LFL revenue decreasing by -3% versus last year.
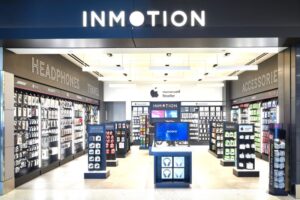
In Air, in the fourth quarter, revenue increased by +13%, up +12% on a constant currency basis, driven by continued investment in the travel essentials format. Air LFL revenue decreased by -2% in the fourth quarter, comprising a -1% decline in LFL revenue in travel essentials and a -3% decline in InMotion LFL revenue. This reflects lower year-on-year passenger volumes in Q4 and softer consumer demand, noted WHSmith.
In Resorts, revenue in the fourth quarter fell -26% year on year reflecting lower visitor numbers and the rationalisation of the fashion store estate, which WHSmith said continued at pace during the second half.
In the Rest of the World division, Q4 revenue slipped by -4%, down -6% on a constant currency basis, as store closures continued in the period. LFL revenue was up +3%.
During the year, WHSmith exited Norway, agreed to exit the Denmark and Sweden markets in early 2027 and will exit the Netherlands on lease expiry in 2027 following a decision not to re-tender the contract.
WHSmith said, “This division is being actively managed both to exit unprofitable stores and transition sub-scale markets to a franchise model in order to improve profitability and cash generation.”
The group completed the sale of Cult Pens in early September 2026.
Following a capital raise on 10 June, the group’s net debt position is expected to be around £325 million at 31 August 2026 with leverage around 2.0x in line with expectations.
WHSmith said its transformation agenda was making good progress, with “strong cost and cash management underpinned by working capital improvements, portfolio rationalisation and targeted capital investment in higher-return travel essentials space”. ✈