
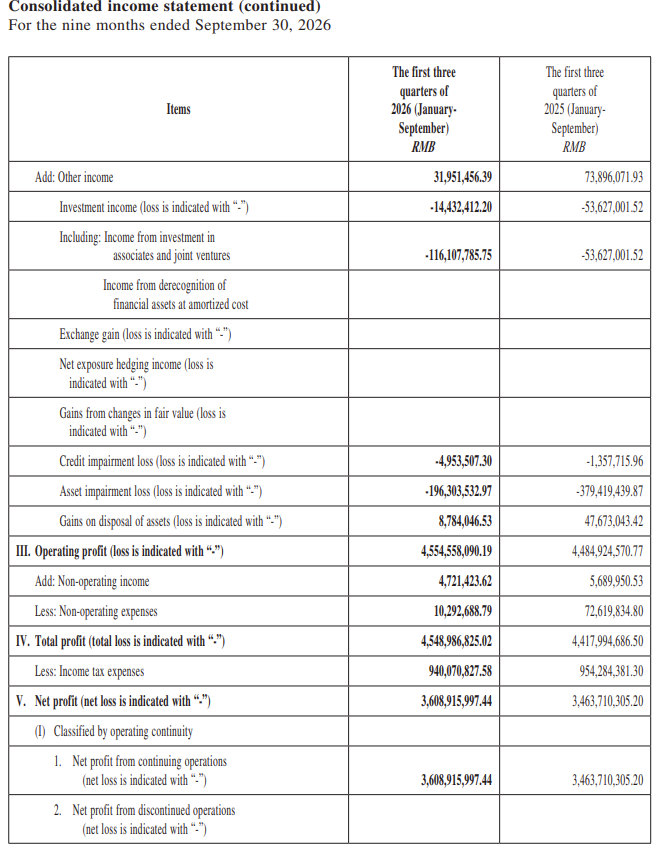
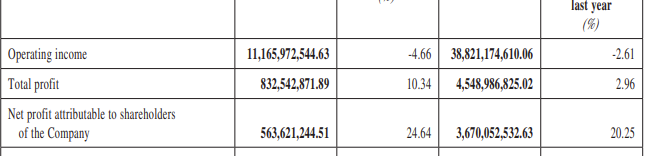
CHINA. China Tourism Group Duty Free Corporation (CTGDF), parent company of China Duty Free Group (CDFG), has posted a +24.64% year-on-year increase in net profits to RMB563,621,244.51 (US$84,613,865) for its third quarter ended 30 September.
The result was against a low base in 2025 when the company recognised a sizeable asset write-down (see Goldman Sachs analysis below).
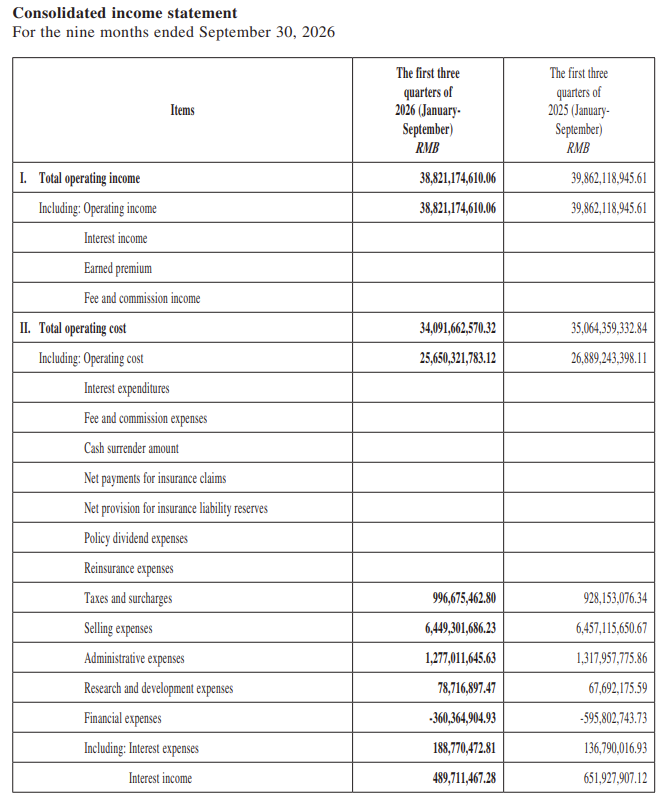
Operating income (revenue) was soft, down -4.66% year-on-year in Q3 to RMB11,165,972,544.63 (US$1,676,296,095).
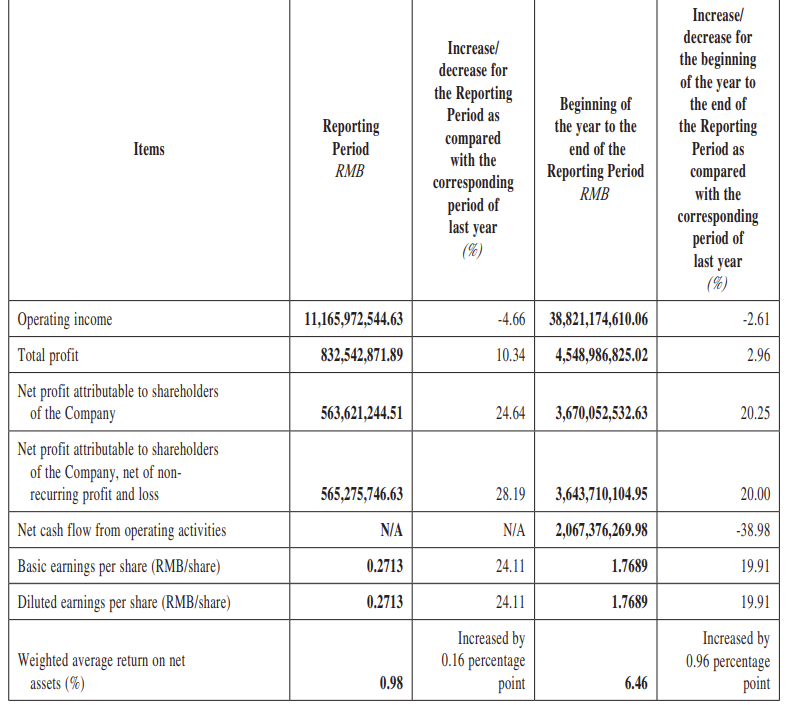
The gross profit margin of CTGDF’s principal businesses (CDFG) continued to improve, increasing by 1.30 percentage points year-on-year in Q3.
For the first nine months net profit rose +20.25% over last year to RMB3,670,052,532 (US$550,968,104) on operating income down -2.61% over the same period in 2025 to RMB38,821,174,610.06 (US$5,828,044,367).
As at 30 September, the company’s market share in the crucial Hainan offshore duty-free market had increased by more than two percentage points year-on-year.
Following the successful completion of the acquisition of DFS’s Greater China retail business earlier this year, the scale of the company’s overseas operations [Hong Kong and Macau are defined as such by CTGDF – Editor] continued to expand.
Driven by the acquisition effect, revenues from CTGDF’s international business soared +71% during the first nine months of 2026.
In July, CDFG partnered with Shanghai International Airport to launch the largest duty-free zone dedicated to Chinese domestic brands at a single airport in the People’s Republic of China.
The zone at Shanghai Pudong International Airport creates a more vibrant showcase for Guochao (国潮 i.e. China Chic) products at an international aviation hub for both domestic and international travellers, the company noted. ✈
Analysis – Goldman Sachs ResearchIn its always insightful analysis of CTGDF results, Goldman Sachs Research noted the Chinese company’s revenue remained soft with Hainan offshore duty-free sales growth further decelerating to +7% year-on-year (vs. +28%/14% in Q1 & Q2). Revenue decline from airport & online channels narrowed to -15% year-on-year (vs. -38%/-23% in Q1 and Q2) as the shop renovations at Shanghai Pudong & Hongqaio and Beijing Capital airports were steadily completed after the respective concessions began in January. Hainan duty-free sales growth softened to +7% year-on-year in Q3 (vs. +28%/+14% in Q1 and Q2) driven by unfavourable weather conditions, particularly in Haikou. 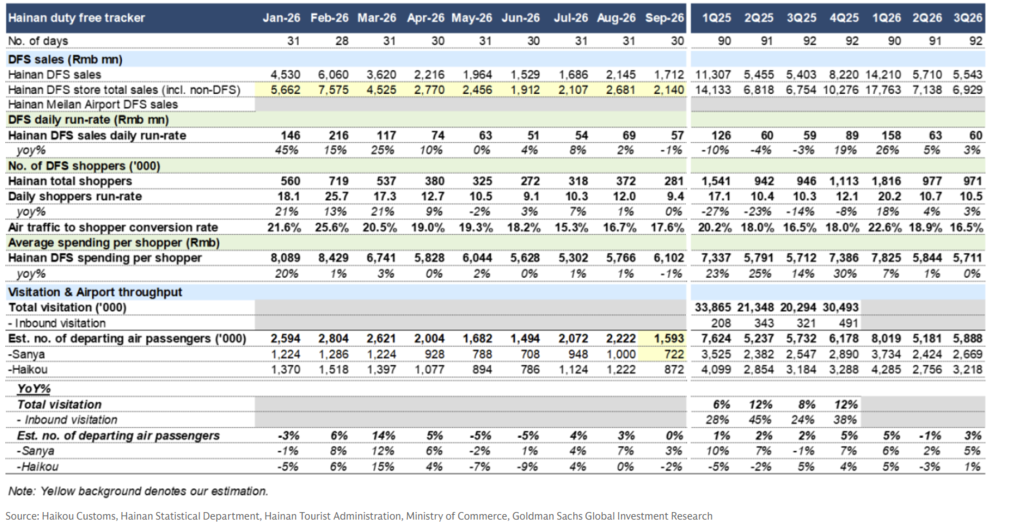 Looking ahead, Goldman Sachs believes that Hainan offshore duty-free sales momentum for the upcoming peak season in Q4 and Q1 2027 will hinge largely on whether the Hainan government will dispense more consumption vouchers – as it did in 2025 and early this year. “The momentum (+3.5% year-on-year) during the recent Golden Week holidays remained quite steady,” the firm said, modelling +3%/+5% year-on-year Hainan sales growth (for the whole sector and CTGDF) in Q4, adding up to +12%/+15% for the full year, respectively. For CDFG’s key airports – Beijing Capital, Guangzhou Baiyun and Shanghai Pudong, total outbound air traffic growth accelerated slightly to +8% year-on-year in Q3 (vs. +6% in Q2). Goldman Sachs highlighted CDFG’s steady gross margin improvement (34% in Q3, up two points year-on-year), which it said was helped by a shift towards higher-margin products (notably watches & jewellery) and procurement cost savings amid the Renminbi’s appreciation against both the US Dollar and the Euro. CTGDF said it will remain “disciplined” on offering pricing discounts amid intense competition from other retail channels, Goldman Sachs pointed out. The firm maintained its neutral rating on CTGDF stock, noting several headwinds (weak consumption sentiment; diversion of traffic to overseas countries; online competition; and the potential impact from a decreased cost advantage upon Hainan turning islandwide tax-free last year) balanced by China’s enhanced downtown duty-free policy introduced in October 2024, which could drive incremental sales to outbound passengers. |