
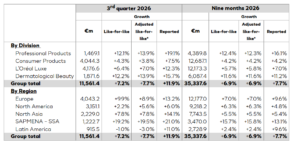
French beauty group powerhouse L’Oréal turned in what CEO Nicolas Hieronimus called an “exceptional” third quarter as sales accelerated +7.7% adjusted like-for-like* growth (+7.2% like-for-like and +11.9% reported) to €11.6 billion.
For the nine months ended 30 September, sales rose +6.9% (both adjusted like-for-like* and like-for-like and +7.7% reported) to €35.33 billion (see table below).
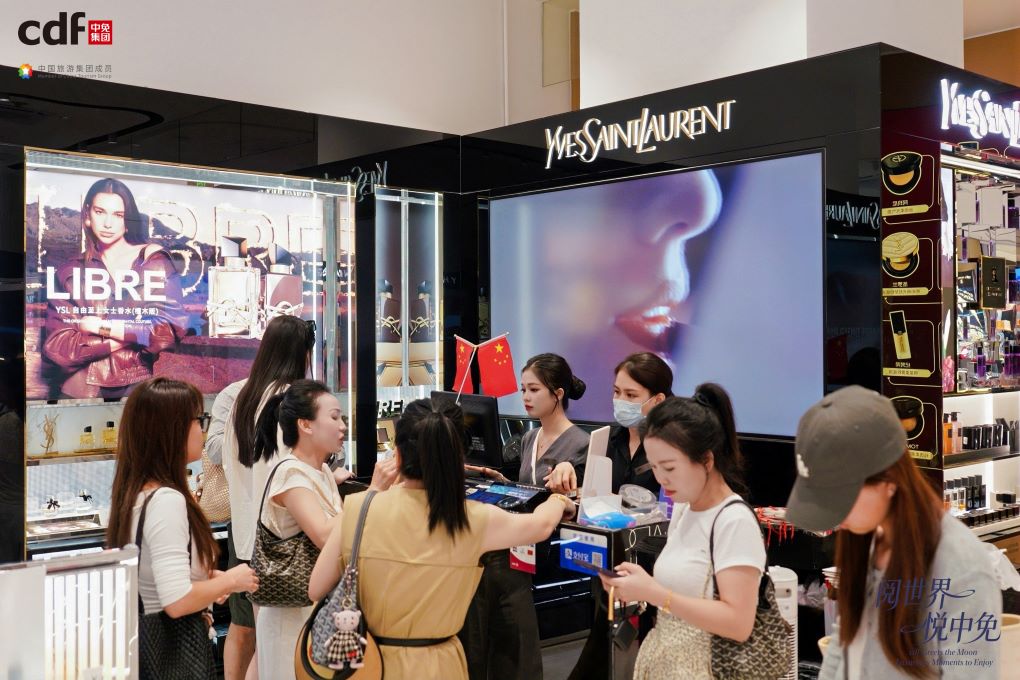
Travel retail performance was encouraging, returning to growth in Q3 and outpacing the market, L’Oréal said. The company also grew in South Korea, fuelled by a rebound in travel activity.
[*Adjusted like-for-like growth factors in the net impact of the phasing of a groupwide IT transformation. Like-for-like growth is based on a comparable structure and identical exchange rates.]
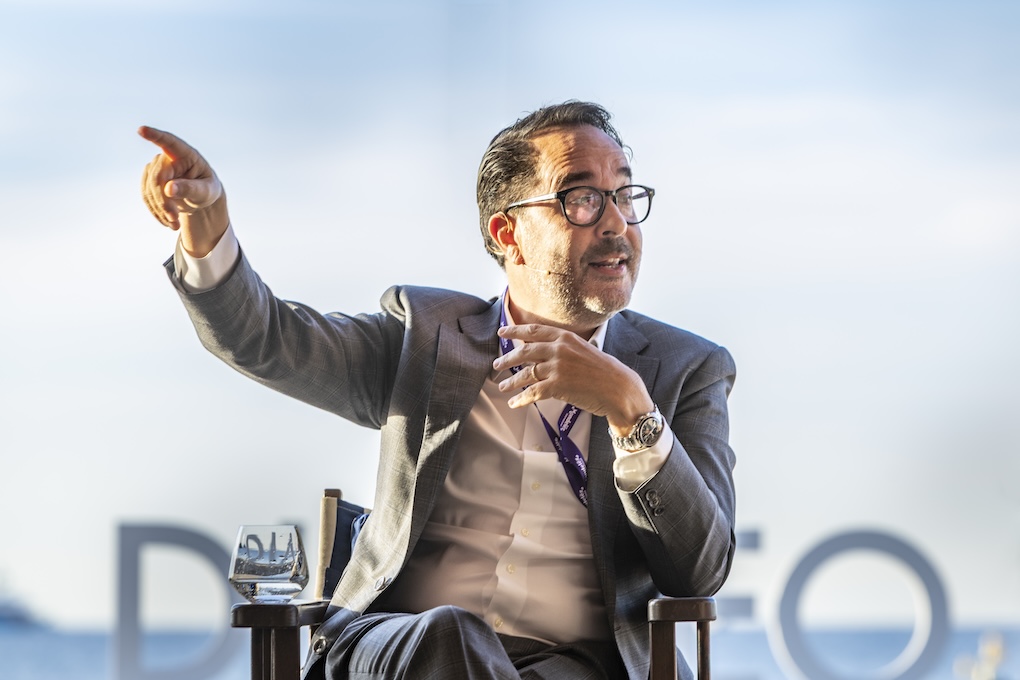
Speaking on the company’s earnings call, Hieronimus said: “In travel retail, we had a very positive Hainan. Mainland China remained a bit negative.” He attributed the latter to previously reported difficulties with the transition of retailers at Shanghai Pudong and Hongqiao airports earlier in the year.
This saw the arrival of Avolta to replace Sunrise Duty Free at Pudong Terminal 1 and Satellite Hall 1 China Duty Free Group taking over from its subsidiary Sunrise at Pudong’s T2 and S2 Satellite Hall and Hongqiao’s T1.
“So we had to re-pipe them with a little bit of inventory. That’s something we won’t have in Q4. And the Korean market was stable,” Hieronimus explained.
Commenting on the channel globally, he said: “As far as travel retail is concerned, the good news overall is that because of both comparatives and the history, the market has turned positive in Q3 globally.
“I am talking global – [we are] still negative in Asia and in North Asia, but less negative, mid-single digit. But positive overall because it has strongly accelerated in Europe. Middle East was OK, not fabulous, but OK. And Americas was positive, too. So we believe the market will be positive.”
The company is at +10% in terms of travel retail sell-in with sell-out at low to mid-single digits, he said. Sell-out in Q4 should be slightly positive or flattish in North Asia, Hieronimus noted.
Outpacing the market
Company-wide, growth was posted across all divisions and regions (including Latin America on a reported basis in Q3) for both reporting periods with “remarkable” performances from Professional Products and L’Oréal Dermatological Beauty and a strong recovery in Luxe.
South Asia Pacific, Middle East, North Africa (SAPMENA) and Sub-Saharan Africa (SSA), collectively titled SAPMENA-SSA, led regional growth, supported by strong momentum across all developed regions.
Fragrances and haircare drove category growth with skincare continuing to accelerate. Ecommerce revenue rose by circa +17%, well ahead of the online market.
Hieronimus commented, “L’Oréal delivered an exceptional third quarter as adjusted like-for-like growth accelerated to +7.7%.
“The global beauty market, once again, proved its resilience in a challenging context – and we continued to significantly outpace it.” {Main story continues below the panel that follows}
On the record with L’Oréal CEO Nicolas Hieronimus
On category showings: Thanks to the success of our innovation plan, we continue to win in haircare and fragrances, and we are outperforming in skincare, a category I was not happy with last year. On regional markets: With the exception of Latin America, sales in all regions grew with a special shout out to Europe and SAPMENA, our #1 and #2 growth contributors in the quarter, and I’m happy to confirm the dynamism of our premium brands in China. On China: China is more than two-thirds of our business in North Asia and then there is travel retail. In China, even though the market slowed down a tiny bit in Q3, it remains dynamic at nine months at somewhere between +2% and +3%. We maintain our growth rate, particularly, of course, favoured by the fact that in the Chinese market the most dynamic parts are the premium part. At nine months, the luxury market is mid-single digit. The dermatological market is a bit higher and professional is mid-single digit. The only part that remains flattish is mass. So that’s favouring us. And within these markets, the most premium brands like Helena Rubinstein, SkinCeuticals and Kerastase are really driving the growth. So we have been really outperforming the market in sell-out. On fragrances: The market is globally growing mid-single digits. And indeed, we are really on a run with our fragrances. We are only in luxury fragrances, of course, but we are growing overall year-to-date close to double digit. I have to say we are adding blockbusters to blockbusters. So we have La Vie Belle and Libre, the #1 fragrance in the world today. Prada with Paradigme and Paradoxe are doing great. And the new ones we’ve launched, and I’m thinking about particularly Armani I Will male fragrances doing phenomenally and Valentino Vendetta is doing good also. 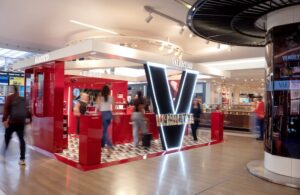 I’m very happy with the performance of Creed, which is also growing double digits. It fills a gap in our premium end fragrances. It has just launched a new fragrance called Iris Debonair, which is doing great. That is also contributing to our overall fragrance performance, both in male and female. On skincare: The acceleration of premium skincare is mainly coming from North Asia. It is really a China phenomenon and part of it is the domestic market where we’re doing great – Helena Rubinstein is growing in high double digits. SkinCeuticals is growing very strongly. There’s also travel retail, where, as always, we are very careful on what we sell in this channel. The biggest growth of the skincare market overall is more driven by the dermatological beauty at all price points. Whether CeraVe, La Roche-Posay or SkinCeuticals, they’re all growing strongly. On haircare: Thanks to the combined strength of Professional Products Division, Consumer Products Division and dermatology with Dercos, we have become the #1 haircare group in the world from a #3 or #2 position three years ago. So the combined efforts of these three divisions is really paying off. On driving top line growth through established and new brands: I am very happy to see that in our top four or five contributors, you’ve got brands like L’Oreal Paris, which is our top #1 contributor, Kerastase, La Roche-Posay and Saint Laurent. These brands are self-generating their growth, but we also have new brands. Prada is in our top ten. It needs to be fuelled. We have Medik8 in skincare, which is growing in the 50 or 60 and all these brands need fuel. I’d rather stick to my margin habits and fuel the top line and therefore, in the end, deliver greater value. On K-beauty: First of all, the boom is real. As far as brands are concerned, it is really growing in skincare. They are innovative, they’re affordable, they’re fast growing. Indeed, I think it’s probably like a +30% growth on average. They are still a small part of the market. In skincare globally, probably all brands put together are 3% to 4% of the skincare market, but it is a phenomenon. And that’s why we acquired two Korean brands. We have 3CE (Stylenanda), which is the #1 Korean makeup brand in the world and which we are rolling out quite successfully in Southeast Asia. That’s also the reason we acquired Dr.G. The roll-out plan we had on Dr.G was, I would say, smooth and starting progressively from the East to the West. But I’ve asked everybody to really gear up and go faster because it’s a speed game. That’s why if you are in the USA today, you would see Dr.G on TikTok Shop. It’s going to be an interesting ride but the brand is already doing very well in Southeast Asia. The big play is to see whether we can also surf on that Korean wave in the West. That’s one of the objectives of Dr.G. ✈ |
 On groupwide performance in a global context: We delivered an exceptional third quarter. Our adjusted like-for-like growth accelerated to +7.7%. As anticipated, the global beauty market growth in the third quarter stood around +5%, confirming the beauty sector’s incredible resilience in challenging times. We significantly outperformed the market across the vast majority of our categories, divisions and regions.
“Driven by the success of our innovation plan and the passion of our teams, we continue to win in haircare and fragrances but are now also outperforming the market in the all-important skincare category.
“Growing well ahead of the market in ecommerce, we continue to double down on this winning channel with spectacular results across all regions, notably emerging markets.
“The impressive results in SAPMENA-SSA, including in India, and the strong performances across all developed regions, with a special mention of Europe, illustrate our local teams’ ability to win across terrains.
“All this underpins my conviction that we are better positioned than ever to win in the long run, leveraging AI to augment the strengths of the L’Oréal model.
“Our performance in the first nine months gives me confidence that L’Oréal will deliver another year of growth in sales and profit, whilst strengthening our global leadership.” ✈
Bellweather buoyancy
In a release, the firm highlighted the French company’s better-than-expected Q3 performance and early signs of competitive “dominance” in large language model beauty discovery. “The margin by which L’Oréal outpaced expectations in its Q3 26 results boosts our confidence that the bellwether’s leadership in beauty is becoming entrenched, as we argued in our Prompting a renaissance: Big Beauty is back report,” the company’s analysts said. “Beyond quarter-specific tailwinds, including a strong sun season, we attribute L’Oréal’s strong performance to its investments in innovation across its entire portfolio and, increasingly, the bellwether’s leadership with regard to LLMs [Large Language Models]. The research firm noted L’Oréal’s like-for-like sales increase of +7.7% in the third quarter, topping consensus estimates by 220 basis points, with volume gains driving over half of that expansion. Analysts also highlighted management’s expectations of +5% beauty market growth and continued “meaningful outperformance”, alongside expected “slight moderation” from the third quarter amid “favourable” one-offs. Against this backdrop, Berenberg raised its sales, EBIT and EPS forecasts for full-year 2026 through 2028 to reflect the latest company commentary and currency movements. The research firm also lifted its price target to €480 from €447, while reiterating its buy rating. Berenberg analysts view L’Oreal’s forthcoming artificial intelligence-focused capital markets day scheduled for 30 November as an important catalyst for the stock. |